Retirement: Why starting late can cost you dearly
For many people, the realisation that retirement is approaching comes with an uncomfortable question: have I saved enough to stop working, or will I have to keep earning an income for as long as I possibly can?
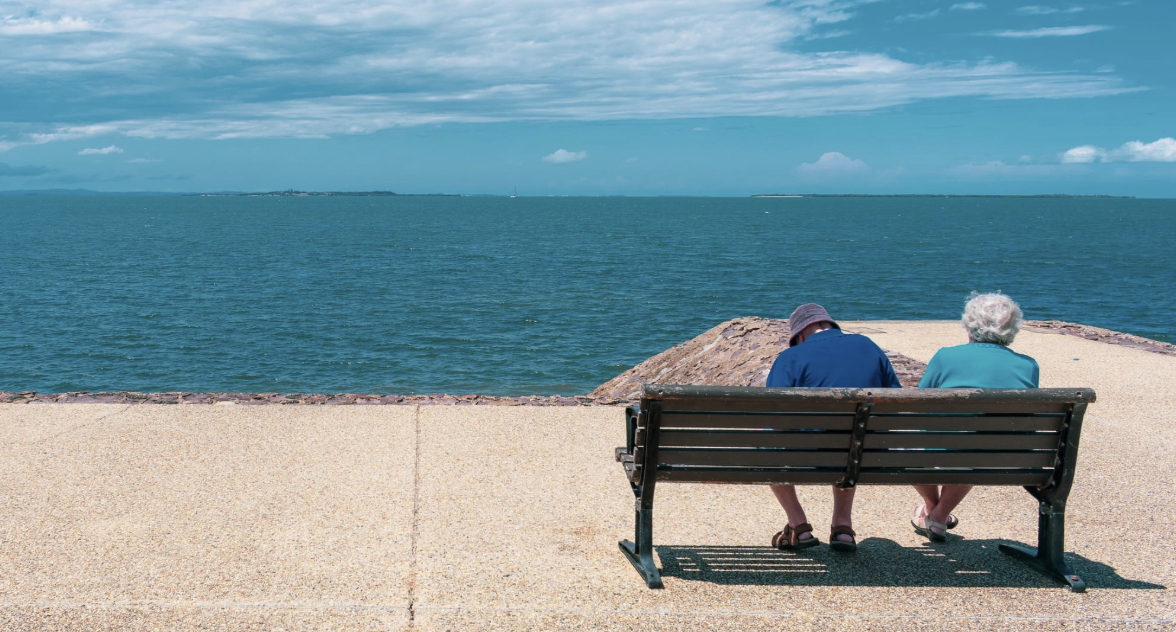
Retirement has a funny way of seeming a lifetime away, until suddenly it isn't. When we are young, there are usually far more immediate things demanding our money and attention than saving for a future that feels impossibly distant. There is rent or a bond to pay, groceries to buy, children to raise, cars to maintain and, if we are lucky, the occasional holiday to enjoy. Saving for old age often falls to the bottom of the list, with the reassuring thought that there will be time to get to it later.
For many people, the realisation that retirement is approaching comes with an uncomfortable question: have I saved enough to stop working, or will I have to keep earning an income for as long as I possibly can? The truth is that life does not always follow the neat financial plan we might have imagined when we were young. Divorce, retrenchment, illness, raising children on a single income, supporting family members or simply earning too little to cover the monthly bills can derail even the best intentions. Sometimes starting again is not a choice, but a necessity.
One of the biggest advantages young people have when it comes to retirement saving is time.
They may not earn much, and they may only be able to put away a modest amount each month, but those savings have something valuable on their side: decades in which to grow. This is where compound growth becomes important. In simple terms, it means earning returns not only on the money invested but also on the returns accumulated over time. The longer the money remains invested, the greater the potential effect of this process.
Of course, telling people to save more is easier said than done. For a young family already struggling to make it to payday, even R200 or R500 a month may feel impossible. With the cost of food, fuel, electricity, housing and education placing pressure on household budgets, there is often very little left at the end of the month. But this is precisely why retirement planning needs to become part of the conversation much earlier in life. It should not be something reserved for people who earn large salaries or have money to spare. Even a small, regular contribution can establish a habit and provide a starting point. As earnings increase, contributions can be reviewed and, where possible, increased.
Those who are fortunate enough to belong to an employer's pension or provident fund should understand how their benefits work, what their employer contributes and what will happen to their savings if they change jobs. People who do not have access to a workplace retirement fund can investigate other suitable options, such as a retirement annuity, with the help of a qualified financial adviser.
It is equally important to understand what happens to retirement savings when life takes an unexpected turn. A job change, divorce or period of financial difficulty can have long-term consequences if retirement money is withdrawn or spent without considering the impact. Before making major financial decisions, it is worth understanding the alternatives and the potential tax consequences.
For those who are already approaching retirement age and have little saved, the situation may feel overwhelming. It is tempting to avoid looking at the numbers because the truth may be frightening. Yet ignoring the problem will not make it disappear. The first step is to establish what is available, including any workplace retirement benefits, savings, investments and other assets, and compare that with expected living expenses. There may still be ways to improve the position. Working for a few additional years, reducing debt, cutting unnecessary expenses, saving whatever is affordable or considering part-time work after formal retirement could all help, depending on individual circumstances. A financial adviser can help assess the options and determine what income might realistically be available.
It is also important to remember that retirement planning is not only about accumulating a large lump sum. It is about creating a reliable income that can support everyday living for what could be 20 or 30 years after leaving full-time employment. Medical costs, unexpected repairs, inflation and the possibility of living longer than anticipated all need to be considered.
Women may face additional challenges, particularly if they have taken time away from paid employment to raise children, worked part-time or experienced a divorce that interrupted their financial plans. These circumstances can affect both their earnings and their retirement savings. Building independent financial security, wherever possible, is therefore important for everyone, regardless of marital status.
Perhaps the most valuable lesson is that retirement planning should not depend on how much money we hope to have one day. It should begin with an honest assessment of our circumstances today and a realistic plan for the future. For younger people, that means resisting the temptation to postpone saving indefinitely. For those in midlife, it means checking whether their current arrangements are sufficient and making adjustments where possible. For those who have reached their sixties without enough put aside, it means facing the situation, seeking advice and making the best decisions available to them now.
There is no point in looking back and wishing we had started ten, twenty or thirty years earlier. Those years have gone. What remains is the opportunity to do something with the years still ahead. Retirement may seem distant when we are young, but time moves more quickly than we imagine. The bills will always need to be paid, the children will grow up, and life will continue to present its unexpected challenges. Yet somewhere among those monthly expenses, a little thought for the future can make a meaningful difference.
The best time to start saving for retirement is when we first begin earning. The second-best time is now. Because one day, the alarm clock will no longer be calling us to work, and we will need to know that the money is there to allow us to answer it on our own terms.
🎶 Laai die playlist hier af. 𝖣𝖾𝗄𝖺𝖽𝖾𝗌 𝗌𝖾 𝗈𝗈𝗋𝗌𝗉𝗋𝗈𝗇𝗄𝗅𝗂𝗄𝖾 𝖠𝖿𝗋𝗂𝗄𝖺𝖺𝗇𝗌𝖾 𝖽𝗂𝗀𝗄𝗎𝗇𝗌 𝗄𝗋𝗒 𝗇𝗎𝗐𝖾 𝗅𝖾𝗐𝖾 𝖽𝖾𝗎𝗋 𝗆𝗎𝗌𝗂𝖾𝗄. 𝖶𝖾𝗅𝗄𝗈𝗆 𝗂𝗇 𝗆𝗒 𝖪𝗅𝖾𝗂𝗇 𝖪𝖺𝗋𝗈𝗈 - 𝖡𝗈𝗅𝖺𝗇𝖽𝗌𝖾 𝖻𝗂𝗇𝗇𝖾𝗄𝖺𝗆𝖾𝗋.
Comments ()